Take the 2,766 English cards whose weekly price history runs all the way back to January 27, 2025, and the median one is up 90.1 percent, with 93.2 percent of them higher than they started. That is the number a Pokémon card investment pitch would quote, and on its own it is misleading, because those 2,766 cards are 13.9 percent of the 19,837 English printings our weekly tape covers at all, and 12.8 percent of the 21,661 printings we price daily. Measure everything over the weeks where we price everything and the median card did not move at all. Both numbers are real. This piece explains why they differ and which one applies to you.
The cards we have watched longest went up a lot
Our weekly price tape reaches back to January 27, 2025 for 2,766 English printings. From that first reading to the latest, the median one is up 90.1 percent and 93.2 percent of them are higher. Value-weighted, treating the group as a single portfolio bought in proportion to price, it is up 110.2 percent. Even against a round-trip cost floor of roughly 24 percent, the figure we published in We Were Wrong About Momentum after modelling marketplace fees, postage and the bid-ask gap, 83.6 percent of them clear.
Deep tape, from January 27 2025 to each card's latest reading, by entry price
| Price when the tape starts | Cards | Median change | Share higher | Share clearing 24% |
|---|---|---|---|---|
| Under $1 | 994 | +75.0% | 92.1% | 82.0% |
| $1 to $5 | 869 | +101.4% | 93.3% | 83.7% |
| $5 to $20 | 568 | +103.7% | 94.4% | 84.5% |
| $20 to $100 | 267 | +111.8% | 94.4% | 88.0% |
| $100 and up | 68 | +86.6% | 92.6% | 79.4% |
There is no price band in that table where the typical card lost money, and the best band is the ordinary middle of the market rather than the expensive end. If this were the whole picture, the answer to the question in the title would be an easy yes.
A long price history is itself a selection
To have a weekly price series reaching back twenty months, a card has to have been continuously listed, continuously priced and continuously interesting for twenty months. Cards that went quiet, fell out of the listings or drifted into the bulk bins do not qualify. So the group is chosen partly on the outcome being measured, which is the same error we retracted a momentum study for in We Were Wrong About Momentum.
The size of that effect is measurable rather than theoretical. Since August 30, 2026 our tape prices 18,340 English printings, most of the catalogue, on the same days. Over exactly those weeks the deep pool and everything else can be compared with no selection at all.
The same weeks, August 30 to September 2026, measured three ways
| Group | Cards | Median change | Share higher | Share unchanged | Value-weighted |
|---|---|---|---|---|---|
| Everything we price | 18,340 | 0.0% | 45.6% | 18.5% | -3.7% |
| The deep-tape pool | 2,461 | +0.7% | 54.3% | 12.5% | +1.5% |
| Everything else | 15,879 | 0.0% | 44.3% | 19.4% | -4.9% |
The deep pool beats the rest of the catalogue on identical weeks, by ten points on the share of cards rising and by six points value-weighted. That gap is the selection, isolated. It says the 90.1 percent figure describes an unusually healthy slice of the market and should not be extended to the catalogue as a whole.
Nothing works until you clear the round trip
Selling a card is not free. Marketplace fees plus postage run to roughly 13 percent of the sale, and buying at the ask rather than the bid costs several points more; our cost model puts the round trip at about 24 percent. Over the three weeks where we price everything, 45.6 percent of cards rose at all and the median rose by nothing, and 6.4 percent of the 18,340 cleared the 24 percent floor. Over twenty months on the deep tape, 83.6 percent did. Holding period is not a detail here; it is the whole mechanism, and The Fee Is a Fixed Cost works through why the floor bites hardest on cheap cards.
What the extremes look like when the entry is real money
Restrict the deep pool to cards that cost at least $20 when the tape starts, so the results are not driven by bulk cards going from twelve cents to forty, and to cards our weekly series is still updating, so both ends of the window are recent, and the spread is still wide.
Deep tape, cards entering at $20 or more and still quoted in the September 2026 run: the extremes
| Card | Set | Jan 2025 | Sept 2026 | Change |
|---|---|---|---|---|
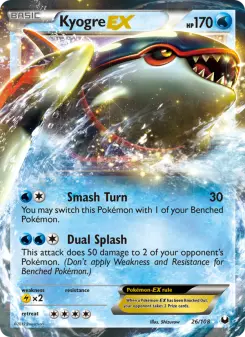
| Kyogre-EX | Dark Explorers | $20.24 | $111.41 | +450% |
| Mimikyu GX | SM - Lost Thunder | $22.16 | $120.38 | +443% |
| Rayquaza GX | SM - Celestial Storm | $26.99 | $144.00 | +434% |
| Pikachu | Generations | $30.16 | $159.68 | +429% |
| Lisia | SM - Celestial Storm | $290.38 | $204.75 | -29% |
| Escape Rope | SM - Burning Shadows | $24.66 | $16.77 | -32% |
| Duraludon VMAX | SWSH07: Evolving Skies | $22.79 | $15.12 | -34% |
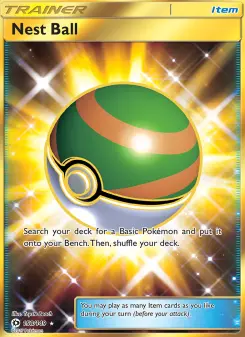
| Nest Ball | SM Base Set | $27.32 | $9.13 | -67% |
Three of the four losers are trainer cards, whose demand is competitive rather than aesthetic, which is the asymmetry Played in 91% of Decks, Worth 24 Cents measured directly: a staple that rotates out of the format loses its only source of demand, while art-driven cards barely notice.
Three things the data actually supports
ONE: liquidity is the variable that matters, not rarity and not nostalgia. The cards with a continuous twenty-month price history beat the rest of the catalogue on the same weeks, and they are identifiable in advance because they are the ones that trade. The Daily Tape lists which cards sell every single day.
TWO: the catalogue is not an index fund. Value is concentrated to a degree that makes 'buy Pokémon cards' meaningless as a strategy: Where the Money Sleeps found 1 percent of cards holding 45 percent of the market's value. Owning the average card is owning nothing.
THREE: measure holding periods in years, not months. Almost nothing in the three-week universal window clears a 24 percent cost floor: 6.4 percent of cards managed it. Most of the twenty-month deep tape did. If the money cannot sit still for years, this is not the asset.
Sources: our weekly price series per TCGplayer product (api_cache rows keyed ppthist), covering the 19,837 English printings that hold such a series; all but one of them also carry a recorded daily ask. The deep pool is every one of those whose series begins on January 27, 2025, the earliest date the weekly tape holds, which is 2,766 cards or 13.9 percent. Long-window changes run from that first reading to each card's latest reading. For 2,421 of the 2,766 that reading is dated September 19 to 22, 2026; the other 345 series stopped updating earlier, the oldest in May 2026, so their window is shorter than twenty months and their changes are included as recorded. The extremes table is restricted to cards still quoted in the September run, which is why a worse loser, Jolteon ☆ at -41 percent, is absent: its series stops on July 28, 2026. The common window runs from each card's first reading on or after August 30, 2026, provided that reading lands by September 5, to its latest, and covers 18,340 printings; the September 5 cutoff keeps the window a genuine three weeks for every card in it, and dropping it would widen the population to 18,651 and the value-weighted change to -4.4 percent; a card is counted as unchanged only when the two readings are identical. Medians use the upper-middle value on even samples. Value-weighted figures are the sum of latest prices over the sum of starting prices, so a dear card counts for more than a cheap one. All prices here are asks, the daily market price a seller is listing at, not completed sales; graded sale medians are a separate tape and are not used in this study. The 24 percent round-trip cost floor is the figure published in our momentum retraction and is a model of marketplace fees, postage and the bid-ask gap rather than a measured transaction cost. Nothing here is financial advice.